Finance teams rarely struggle because QuickBooks is missing features. They struggle because billing information lives in too many places at once.
A project manager approves work in email. A salesperson updates the deal value in the CRM. Purchase orders arrive as PDFs. Hours sit in a spreadsheet. The billing terms are in a contract that accounting doesn’t see until month-end. The result is familiar: late invoices, duplicate data entry, inconsistent records, and finance staff chasing information instead of reviewing it.
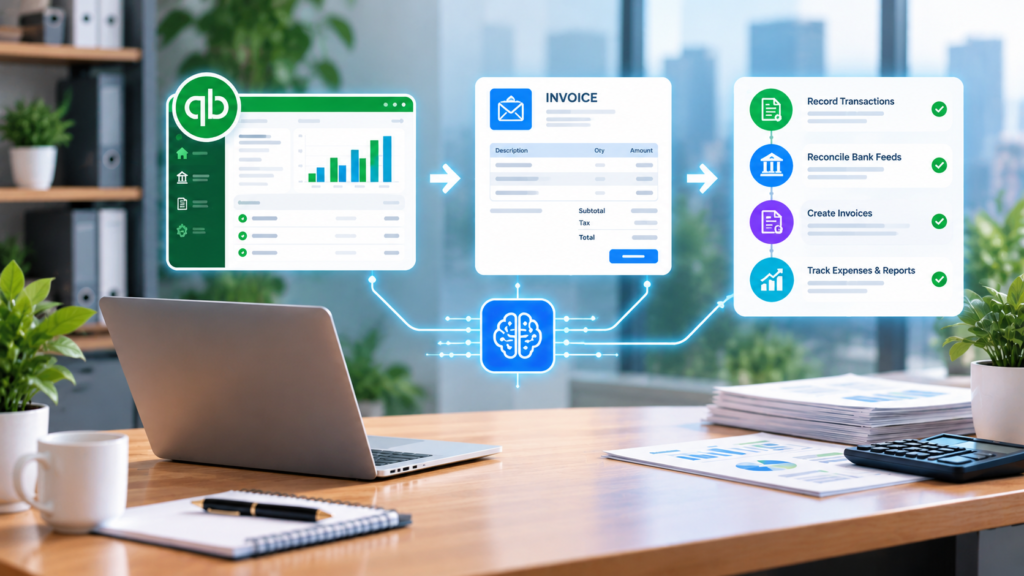
AI QuickBooks automation helps with exactly that. It doesn’t replace the accounting team. It gathers, extracts, routes, and syncs financial information across the systems you already use, so invoices go out faster, receivables move sooner, and approval controls stay intact.
Why Finance Workflows Still Depend on Manual Work
A single invoice can depend on a CRM record, a project milestone, an email approval, a contract, a timesheet, and a customer PO. QuickBooks only sees the end result.
QuickBooks’ built-in automation handles structured work well: recurring invoices, bank rules for transaction categories, scheduled reminders, and bank feed matching. It struggles with unstructured instructions. Picture an email to accounts receivable that says, “Please invoice the remaining 50% after installation approval.” A person understands it immediately. A rule-based tool has nothing to trigger on.
That’s the gap AI for accounting fills. It reads emails, documents, and approvals for operational context, then starts the right workflow. This matters because most finance delays happen before the data ever reaches the accounting system.
What AI Adds to QuickBooks Automation
AI is most useful as a workflow layer around QuickBooks, not a replacement for it. QuickBooks stays the financial system of record. AI moves information in and out of it more reliably.
A platform like Aimey.ai can read incoming emails and attachments, extract billing details from contracts and POs, detect invoice triggers in CRM updates, run approval workflows, suggest payment matches, send reminders, and surface bottlenecks. Each of those steps either prepares work for a person or acts within limits a person has set.
That’s the core principle here. AI accounting workflows remove repetitive handling, and financial judgment stays with the finance team.
Practical Ways to Use AI with QuickBooks
Can AI automate QuickBooks? In many areas, yes. The more useful question is which workflows benefit most.
Creating Invoices From CRM Deals and Approved Work
For many service organizations, invoicing is dependent on a sequence of steps. Sales closes the deal. Operations delivers. Approval arrives via email or slack. Finance creates the invoice by copying details from 3 systems.
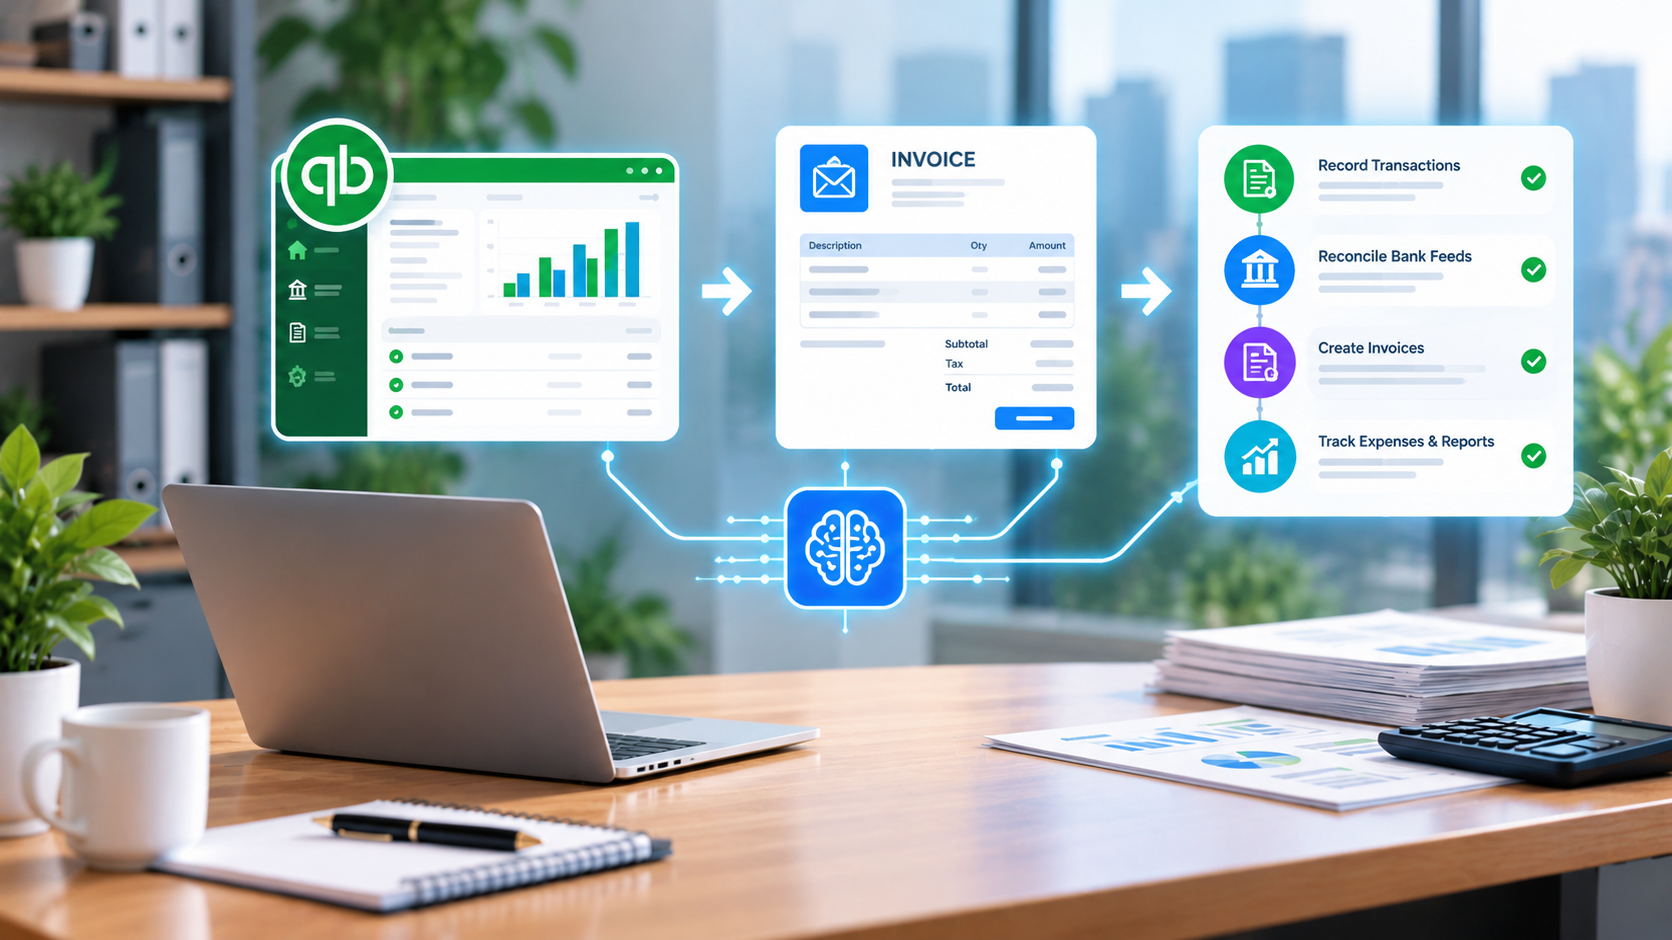
Or Aimey.ai may watch for the trigger instead. That may be a CRM deal stage changing to “Implementation Complete,” a project milestone being signed off, or a client acceptance email. It then takes in the billing details and approved pricing and prepares a draft invoice in QuickBooks for finance to verify before sending it out. Billing cycles are shorter, and fewer invoices are missed. Custom price, contested scope, tax treatment and odd terminology still require a person to check them.
Extracting Billing Details From Contracts and POs
Finance teams commonly examine contracts manually to identify the billing schedule, PO number, payment milestones, legal entity and net terms. AI can pull these facts out of contracts, statements of work, and POs and then check them before an invoice is generated. If a customer’s PO requires a reference number, department code or split invoicing, the process may identify what’s lacking up front, which means fewer rejected invoices. Accountants should still look at advanced contract language, multi-entity billing, and anything with revenue recognition implications.
Keeping Customer and Vendor Records in Sync
The billing address is updated in CRM but not in QuickBooks. Vendor updates tax details; no one tells finance. AI can watch email, forms, and CRM modifications and recommend corresponding changes across systems to keep CRM and accounting data aligned. It can also find duplicate vendors and missing tax IDs. Changes to vendor bank details should always be subject to specific approval. They’re a regular target for payment fraud.
Categorizing Transactions
Bank rules bring you to a consistent vendor but break when descriptions change. AI can recommend account mappings with a confidence score based on prior categorization, vendor history, and supporting documents. Routine stuff goes fast, while anything large, weird, capital-related or tax-sensitive goes to a bookkeeper.
Using AI for Receivables and Finance Visibility
Matching Payments to Invoices
QuickBooks bank feed matching handles simple payments. It becomes more difficult if a customer pays part of an invoice, makes one transfer for three bills, leaves off the reference number or sends remittance details in another email.
AI can examine quantities, client history, remittance emails and open bills to recommend the most likely matches, then send anything uncertain to an exception queue. Reconciliation is quicker, and staff time is spent on true differences, disputed balances and substantial changes.
Automating Reminders and Overdue Follow-Ups
Collections follow-up is important, and it’s usually the first thing dropped when finance gets busy. AI can run a consistent collections process based on invoice age, payment history, and contract terms, with escalation built in. For example:
- At 7 days past due, a friendly reminder goes out automatically.
- At 30 days, a review task is created for the finance team.
- At 60 days, leadership is notified, and someone decides on the next step.
Because Aimey.ai can see the account’s history, reminders can reference the actual invoice and conversation instead of a generic template. Relationship decisions, like payment plans or disputes, stay with people.
Finance Summaries and Bottleneck Detection
Preparing reporting usually starts with pulling data from several systems. AI can bring together invoice activity, AR aging, payment trends, and approval delays into a regular summary for the controller. It can also follow the process across systems and show where it slows down: sales approvals that arrive late, POs missing references, project sign-offs that stall, and invoices that keep needing corrections. That’s visibility small finance teams rarely have time to build by hand. Final reporting and forecasting stay with finance leadership.
How to Build an AI-Assisted QuickBooks Workflow
Automate one workflow at a time instead of attempting a full finance transformation. Invoice creation, payment matching, and reminders are good first candidates.
- Pick the process and its trigger, for example a CRM deal reaching a defined stage.
- List the data sources the workflow needs: CRM, email, contracts, project tool.
- Define approval checkpoints for what needs a person before anything posts or sends.
- Set confidence thresholds and an exception queue, so uncertain items are routed to a named owner instead of guessed.
- Log every action with its source document and approver for the audit trail.
- Run it in parallel with the manual process, compare results for a cycle or two, then expand.
Design the controls first and layer automation on top. That order is what makes finance automation trustworthy.
What Should Not Be Fully Automated in Finance
AI is strongest on structured, repeatable work. Judgment calls stay with finance professionals.
| Let AI prepare and route | Keep a person accountable |
| Draft invoices from approved work | Final financial approvals |
| Billing detail extraction | Revenue recognition decisions |
| Payment match suggestions | Write-offs and credit decisions |
| Reminder schedules and escalation tasks | Tax decisions |
| Categorization suggestions | Changes to vendor banking details |
| Finance summaries and bottleneck reports | Regulatory reporting and high-value payments |
Even within the left column, send work to a person when confidence is low, contracts are complex, amounts are material, or the same exception keeps coming back.
Common Finance Automation Mistakes
Most failed finance automation projects start with an unclear process. If source data is messy, approvals are informal, and nobody owns exceptions, automation makes those problems faster and harder to see.
A related mistake is expecting AI to figure everything out. It still needs defined business rules, a mapped integration between systems, testing against real invoices, and someone responsible for maintaining the workflow when processes change.
The third is automating too much too early. A finance team that sees AI make an unexplained change to the books will stop trusting the system, and that trust is slow to win back. Companies that treat automation as gradual process improvement, measured and expanded step by step, get better long-term results than those chasing full autonomy.
How to Measure the Impact of Finance Workflow Automation
Capture a baseline before launch, then track process outcomes.
| Metric | What it tells you |
| Invoice cycle time (work approved to invoice sent) | Whether billing is actually faster |
| Days sales outstanding (DSO) | Whether invoicing and follow-ups speed up cash collection |
| Manual touches per invoice | How much handling is left |
| Invoice error and rejection rate | Whether extraction and validation are working |
| Payment matching accuracy | Whether suggested matches can be trusted |
| Exception frequency | Where rules or source data need fixing |
The goal is better consistency and visibility, not just fewer hours. In many small and midsize finance teams, the biggest gain is that people spend their time reviewing exceptions and analyzing performance instead of chasing documents.
FAQs
Is AI able to automate QuickBooks?
Yes, for many jobs in everyday life. It can generate invoices, classify transactions, reconcile payments, send reminders for payment, and generate reports. The real financial data remain in the hands of QuickBooks. AI just does some of the work that goes on around them.
How does AI automatically generate invoices?
There’s a trigger to it. Or it may be a contract that is at a certain point in your CRM, a project milestone that has been approved, or an email verifying that work is ready to charge. AI takes the client and pricing details, prepares the invoice in QuickBooks and sends it to finance for a quick check before it goes to the customer.
Is AI usable for invoice reminders?
Yes. You don’t want someone on the finance team to manually check each past-due invoice. AI can send reminders based on the age of an invoice, the customer’s payment history, and the rules you define. And if you want a more personal follow-up, it can flag the account for the finance staff.
What accounting tasks shouldn’t be completely automated?
There are some calls that you can’t delegate to AI altogether. Tax decisions, final financial approvals, revenue recognition, write-offs, regulatory filings and changes to vendor bank details all require supervision by humans. Artificial Intelligence can do the hard work, but the final decision should be made by finance.
Conclusion
AI QuickBooks automation is less about replacing accounting personnel and more about eliminating the friction around their work. The main inefficiency in finance is disconnected systems, fragmented approvals, and duplicate data entry, not the accounting software.
AI-assisted workflows gather the information and move it where it needs to go. The outcome is speedier invoicing, clearer receivables, fewer manual errors and more uniform operations. The businesses that benefit the most from it aren’t seeking to take people out of finance. They allow AI to perform repetitive coordination while their financial people handle approvals, exceptions, analysis and conclusions.